Negotiating a car loan can feel overwhelming, but it doesn’t have to be. Understanding the key factors that influence loan terms can empower the buyer during the negotiation process. Researching interest rates, understanding credit scores, and knowing the value of the vehicle are crucial steps to securing a favorable loan.
Buyers should approach negotiations with confidence and be prepared to ask questions. By comparing offers from different lenders, they can leverage competitive rates to their advantage. Knowing the details allows for informed decisions that can save thousands over the life of the loan.
Effective negotiation also involves clear communication and understanding of one’s own financial situation. Whether it’s discussing loan length or monthly payments, being assertive can lead to better terms. Buyers who are well-prepared can navigate the process successfully and leave with a deal that meets their needs.
Understanding Car Loans22 March 2025
Car loans are essential financial tools that allow individuals to purchase vehicles without paying the total cost upfront. Recognizing the key components of these loans is crucial for making informed decisions.
Loan Terms and Conditions
Loan terms outline the agreements between the borrower and the lender. This includes the loan amount, repayment period, and any fees associated with the loan. Common terms range from 36 to 72 months. A longer term may result in smaller monthly payments but could lead to higher interest costs.
It’s vital to read the fine print. Conditions may include penalties for early repayment or fees for late payments. Understanding these terms can prevent costly surprises down the line.
Interest Rates Explained
Interest rates significantly impact the total cost of a car loan. They usually vary based on factors like market conditions, loan term, and the borrower’s creditworthiness. Rates can be fixed or variable; fixed rates remain the same throughout the loan term, while variable rates can fluctuate.
Borrowers should shop around to find competitive rates. Even a small difference in interest can lead to substantial savings over time. Using online calculators can help individuals estimate their monthly payments based on different rates.
The Impact of Credit Score
A credit score is a critical factor in determining loan eligibility and interest rates. Lenders use it to assess the risk of lending to an individual. Higher credit scores generally result in better terms, including lower interest rates and reduced fees.
It’s essential for borrowers to check their credit reports before applying for a loan. Identifying any inaccuracies or addressing issues can improve a score. Proactive credit management could open doors to more favorable loan conditions.
Preparing for Negotiation
Preparation is crucial for a successful car loan negotiation. Knowing your financial limits and understanding the current market rates can significantly influence the outcome. This section addresses key components of preparation.
Assessing Your Budget
Before negotiating a car loan, it is essential to assess personal financial circumstances. This involves reviewing income, existing debts, and monthly expenses. A clear budget helps determine a comfortable monthly payment without straining finances.
- Income and Expenses: Calculate fixed and variable expenses. Make room for unforeseen costs.
- Debt-to-Income Ratio: This ratio should ideally be below 36%. A lower ratio strengthens bargaining power.
By determining how much can be reasonably spent on a loan, one can confidently approach lenders with a clear stance.
Researching Market Rates
Understanding prevailing interest rates can significantly impact negotiation effectiveness. Researching offers from various lenders informs individuals of fair rates relative to their credit profile.
- Credit Score Impact: A higher credit score often yields better rates. Know your credit score before negotiations.
- Local Market Trends: Rates can vary regionally. Analyze local market conditions to better gauge expectations.
Potential borrowers can visit financial websites or consult lenders to gather necessary information. This knowledge equips them to make informed decisions during discussions.
Pre-Approval Advantages
Seeking pre-approval for a loan offers distinct advantages in the negotiation process. It provides a clearer picture of the loan amount one qualifies for and affirms seriousness to lenders.
- Clear Limits: Pre-approval establishes a specific budget, allowing one to focus on viable options.
- Stronger Position: Lenders may view pre-approved borrowers as less risky, possibly improving negotiating terms.
Car buyers should approach multiple lenders to ensure competitive offers. A pre-approval can streamline the entire process and enhance confidence during negotiations.
Negotiating Strategies
Effective negotiation strategies can significantly improve loan terms and help secure a favorable deal. Focusing on how to initiate conversations, discuss important terms, and utilize trade-ins can lead to better outcomes.
Starting the Conversation
Beginning negotiations with confidence sets the tone for the entire process. It’s essential to enter the dealership prepared. Research current market rates, loan offers, and potential lenders. This information provides leverage during discussions.
Be polite but assertive. Introduce oneself clearly and express an interest in finding the best possible terms. It’s advantageous to show awareness of the dealership’s offerings and any special promotions.
Establishing rapport with the salesperson can facilitate smoother negotiations. A friendly demeanor combined with clear goals strengthens the negotiation position.
Discussing Terms and Rates
When discussing loan terms, focus on key factors such as interest rates, loan duration, and monthly payments. Understanding these elements helps clarify the offers from lenders.
Ask specific questions:
- What is the interest rate?
- Are there any fees?
- What happens if payments are missed?
Having a straightforward checklist can streamline this process. For instance, a clear comparison of offers can help identify the best deal. Remaining flexible during discussions allows adjustments based on counteroffers while staying within budget.
Negotiators should be ready to counter any unfavorable terms presented by the dealer. This includes having alternate financing offers prepared as leverage.
Trade-In Tactics
Using a trade-in wisely can enhance overall negotiation power. Prior to negotiations, the seller should assess the value of their current vehicle through multiple online valuation tools.
Timing also plays a crucial role; negotiating trade-in values before discussing new loan terms often leads to better offers. It’s important to focus on the car’s condition and market demand during the appraisal process.
Being informed about the vehicle’s worth helps in countering low trade-in offers. If the dealer gives an unsatisfactory value, the seller can negotiate based on similar vehicles available on the market.
Closing the Deal
When finalizing a car loan, understanding the details of the financing agreement is crucial. Clear comprehension of the terms and conditions can significantly impact overall satisfaction and financial responsibility.
Understanding the Agreement
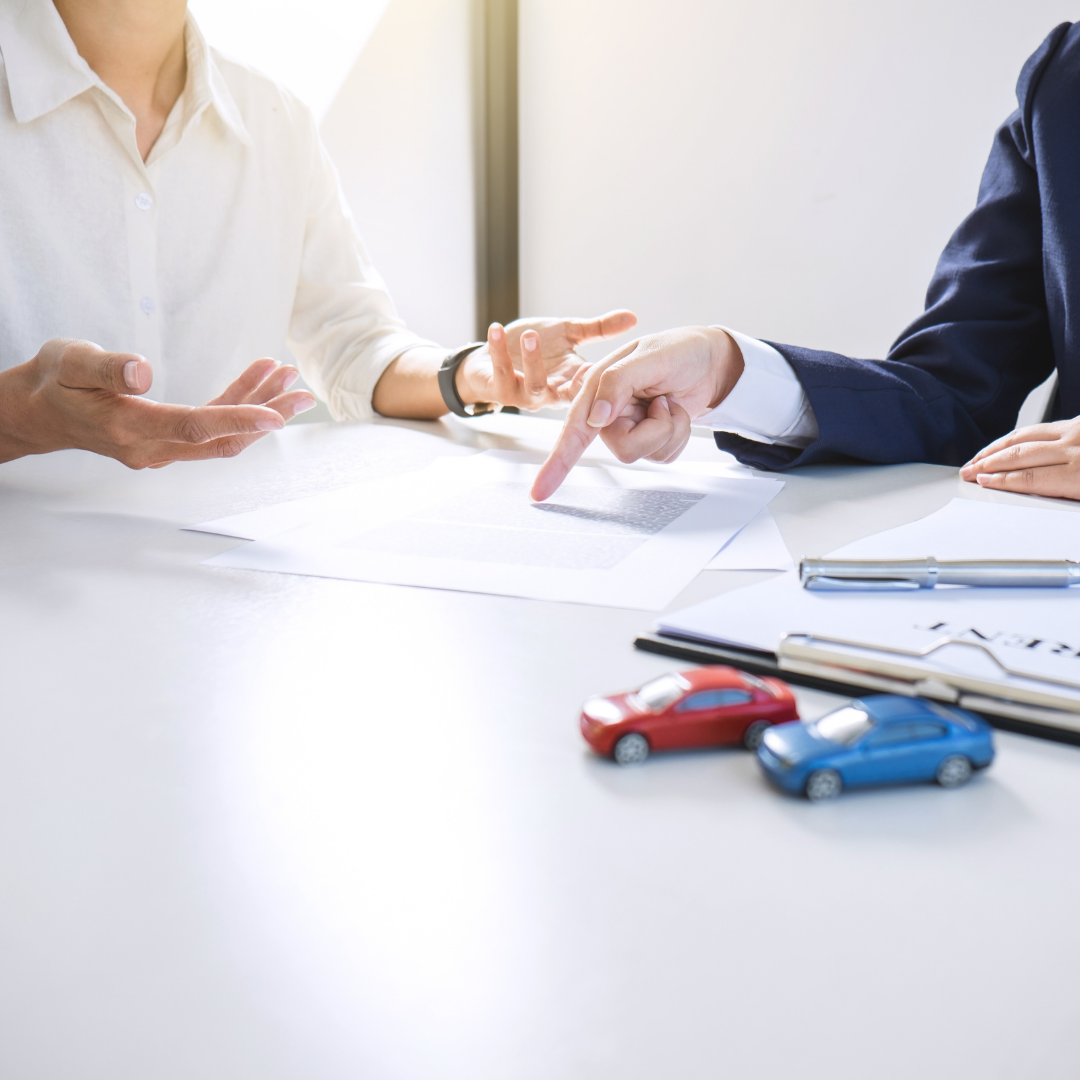
Before signing, it is essential to review all aspects of the loan agreement. Key components include the loan amount, interest rate, term length, and monthly payments.
- Loan Amount: This should reflect the price negotiated for the vehicle.
- Interest Rate: Identify whether this is fixed or variable; lower rates save money.
- Term Length: Commonly 36 to 72 months, consider how it fits into budget constraints.
Look for any additional costs such as origination fees, prepayment penalties, or optional add-ons. These factors can affect the total cost of the loan and should be thoroughly understood.
Finalizing the Loan
After reviewing the agreement, it is time to finalize the loan. Communicate any concerns regarding terms to the lender before proceeding.
- Submit Documentation: Lenders may require proof of income, credit history, and other financial information.
- Negotiate Terms: If certain terms seem unfavorable, now is the time to negotiate.
- Read the Fine Print: Before signing, ensure understanding of all clauses, including payment schedules and penalties.
Successful negotiation can lead to more favorable terms and lower costs, ensuring a smoother ownership experience.